By Dr. Tamara Patzer
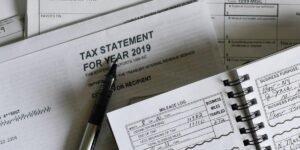
Self-employed workers who use part of their home for business can deduct up to $1,500 a year under the Internal Revenue Service’s simplified method, according to Publication 587, the IRS’s current edition (tax year 2025). As of November 2026, the IRS shows no 2026 edition and lists no changes to the rule. The rule matters to remote contractors, including people who review artificial intelligence output from a spare bedroom, because a home office is often their largest fixed workplace cost. Employees working from home do not qualify, the publication states.
Key Takeaways
- IRS Publication 587 (2025) says self-employed persons and partners can claim the home office deduction, and that an employee using part of a home does not qualify.
- The space must be used regularly and exclusively for the business, with two exceptions: storing inventory or product samples, and running a licensed daycare.
- The simplified method multiplies $5 by the square footage of the office, up to 300 square feet, for a maximum deduction of $1,500 a year.
- The deduction cannot exceed the gross income from the business use of the home, minus business expenses unrelated to the home.
- Actual-expense filers use Form 8829, and the deduction is reported on Schedule C.
Who Qualifies
Publication 587, titled Business Use of Your Home, covers individuals who run a trade or business. It says self-employed persons and partners can claim the deduction. Its flowchart states that an employee who uses part of a home does not qualify. The IRS makes the deduction available to homeowners and renters across all types of homes, according to its home office deduction page, which was last reviewed on September 11, 2024, and is marked as historical.
For contractors paid on a Form 1099-NEC, the distinction is basic. The Expert Opportunity Report, which tracks remote contract roles for AI companies, notes in its guide to reading a listing that a Form 1099-NEC treats a worker as self-employed, with pay reported on Schedule C and self-employment tax applying to net earnings of $400 or more, per an IRS FAQ reviewed September 28, 2026.
The Exclusive-Use Test
The publication requires the specific area of a home to be used regularly and only for the trade or business. Shared personal and business use disqualifies the space. A desk in a living room that doubles as family space is the kind of setup that may fail the test, while a spare room used only for work is the IRS’s own example of a qualifying space.
The IRS lists two exceptions that do not require exclusive use. One covers storing inventory or product samples when the home is the only fixed location of the business. The other covers operating a licensed daycare facility.
Principal Place Of Business
A home office qualifies as a principal place of business if it is used regularly and exclusively for administrative or management activities and the taxpayer has no other fixed location where those activities take place in substantial amounts. Other paths exist. A taxpayer who meets patients, clients or customers at home may qualify, as may one who uses a separate structure, such as a studio or greenhouse, in connection with the business. The IRS home office page also states that an office that is merely appropriate and helpful to the business does not support a deduction.
How The Simplified Method Works
The simplified method replaces the tracking of actual home expenses with a flat rate. The taxpayer multiplies $5 by the allowable square footage, which is capped at 300 square feet, so the largest possible deduction is $1,500 a year. A 120-square-foot room, for example, produces $600. A taxpayer who uses the simplified method cannot also deduct actual expenses or depreciation for that space. Tax rules can change from year to year, so readers should check IRS.gov or ask a tax professional for the current year’s rate and limits before filing.
The IRS says the simplified option has been available for tax years beginning on or after January 1, 2013. The regular method, which deducts actual expenses such as mortgage interest, insurance, utilities, repairs, and depreciation based on the percentage of the home used for business, remains available. The IRS home office page says the regular method was the only option for tax years 2012 and earlier.
The Income Limit
Publication 587 states that the deduction cannot exceed the gross income from the business use of the home minus business expenses that are unrelated to the home. If those unrelated expenses exceed that gross income, the deduction for that use is not allowed. In practice, a contractor with a slow quarter or a project that has not paid yet may find the deduction limited.
Forms And Reporting
Taxpayers using actual expenses file Form 8829, Expenses for Business Use of Your Home, and the IRS says the form is required for self-employed filers who choose the regular method. Taxpayers using the simplified method complete a worksheet found in the Schedule C instructions. Either way, the deduction is reported on Schedule C, where Publication 587 cites line 30.
The Size Of The Group Affected
The Bureau of Labor Statistics reported in its Contingent and Alternative Employment Arrangements release, issued November 8, 2024, that 11.9 million workers, or 7.4% of total employment, were independent contractors in July 2023. That is the most recent figure the bureau had published at that time for the group, and it describes all kinds of independent work, not only remote or technology work.
Frequently Asked Questions
Can an employee who works from home claim the deduction?
No. Publication 587 states that an employee using part of a home does not qualify.
What is the most the simplified method allows?
$1,500 a year, which is $5 per square foot on up to 300 square feet.
Does a room have to be used only for work?
In general, yes. The IRS requires regular and exclusive use, with narrow exceptions for inventory storage and licensed daycare.
Where can I read more about contractor taxes and listings?
The Expert Opportunity Report publishes a plain-language guide, how to read an AI expert job listing before you apply, and a free newsletter of open roles. A tax professional can answer questions about a specific return.
Dr. Tamara Patzer is a publisher and former newspaper editor who writes about AI and business data.
You may reach her through: info@dailysuccessinstitute.com
Sources: Internal Revenue Service, Publication 587, Business Use of Your Home (2025 edition, the latest published as of November 2026; IRS publication page reviewed June 6, 2026); IRS, Home Office Deduction page, last reviewed September 11, 2024; U.S. Bureau of Labor Statistics, Contingent and Alternative Employment Arrangements, released November 8, 2024; Expert Opportunity Report, how to read an AI expert job listing (November 11, 2026).
Disclaimer: This article is for general informational purposes only and does not constitute tax, financial, legal, or professional advice. Tax regulations, deduction limits, eligibility requirements, and other information may change and vary depending on individual circumstances. Readers are encouraged to verify information through official sources and consult a qualified professional before making tax or financial decisions. No specific financial benefits, savings, or outcomes are guaranteed.